Short-term employment 2026 and 2027: the 70-day rule for event staff
When festival casual staff stay exempt from social insurance, how the 70 days and 3 months are counted, what applies to two jobs at once, whether the 70-day rule is tax-free, what 'occupational' (berufsmäßig) means, and where organizers blow the limit.
In short
- Short-term employment (kurzfristige Beschäftigung) is work that lasts at most 3 months or 70 working days within a calendar year and is not done on an occupational (berufsmäßig) basis. In that case, no social-insurance contributions apply.
- All short-term engagements within the calendar year are added together, including with other employers. The employer must ask about prior employment at hiring and document the answer.
- The limit is most often blown by crew who work for several organizers over the summer. Whoever doesn't ask about prior employment is liable for the contributions.
- § 8 Abs. 1 Nr. 2 SGB IV
- § 8 Abs. 2 SGB IV
- § 40a Abs. 1 EStG
- Geringfügigkeits-Richtlinien der Spitzenorganisationen der Sozialversicherung
Under § 8 Abs. 1 Nr. 2 SGB IV, short-term employment (kurzfristige Beschäftigung) is employment limited within a calendar year to at most three months or 70 working days, and not carried out on an occupational (berufsmäßig) basis. It is exempt from contributions across all branches of social insurance. For organizers, this is the employment form for most of the festival crew: students, retirees, people with a main job elsewhere, who help out for a few days over the summer. The limit isn't counted per event, but per person and per calendar year, across all employers.
The 70-day rule at a glance
| Question | Answer |
|---|---|
| Time limit | 3 months or 70 working days in the calendar year, across all employers combined |
| What counts as a day | Every calendar day with work, however many hours |
| Social insurance | No contributions, neither from the person nor from the employer |
| Tax | Not tax-free: individual wage tax or a flat 25 percent |
| Earnings limit | None; above €603 a month (2026) or €633 (from 2027), occupational character has to be checked |
| Registration | With the Minijob-Zentrale, person group 110 |
| Employer's duty | Ask about prior employment in the calendar year and document it |
Who is allowed to be short-term employed
Three conditions must all be met at once:
- Time limit: at most 3 months or 70 working days in the calendar year. The limit has to be agreed from the outset, in the contract or by the nature of the engagement — for example, a festival from September 8 to 10.
- No occupational character (Berufsmäßigkeit): the employment must not be of significant economic importance for the person. Students, pupils, retirees, homemakers, and people with a main job are unproblematic. Problematic are unemployed people, people between school and vocational training with no other coverage, and anyone who earns their living predominantly from such jobs.
- No aggregation over the limit: all short-term engagements for the year are added up. 40 days at the spring festival, 20 days at the open-air, and 15 days at the trade fair make 75 days. The last engagement becomes subject to social insurance.
The amount earned doesn't matter for social insurance purposes. A short-term engagement is allowed to bring in more than the Minijob threshold. Earnings only decide whether occupational character has to be checked: above the marginal-employment threshold, €603 a month in 2026 and €633 from 2027, the employer has to check it. Below it, the engagement stays exempt even if it would be occupational. How the Minijob threshold is derived is covered in the article on the Minijob limit 2026 and the handbook entry on Minijobs at events.
70 working days or 3 months: which applies and how to convert
The umbrella social-insurance bodies set out in the Geringfügigkeits-Richtlinien (marginal-employment guidelines) which threshold applies:
| Employment | Standard |
|---|---|
| At least 5 days a week | 3 months (calendar months or 90 calendar days) |
| Fewer than 5 days a week | 70 working days |
Event crew almost always work on individual days or weekends, so the 70-working-day threshold applies. Every calendar day with work performed is counted. A build day from 6 am to 10 pm is one day. A night shift from 8 pm to 4 am is, under prevailing practice, also one day, as long as it's a single continuous shift.
There is no conversion of 70 days into months; the two limits stand side by side. The difference matters when several engagements are added up: then 90 calendar days replace the 3 months, and a full calendar month counts as 30 days. Someone who worked a full month full-time for a caterer in July and then weekends at a festival has two engagements with two yardsticks. Which limit applies should be recorded for the person by the payroll office.
How it's counted
The employer must check, at the start of the engagement, whether the limit will be met within the current calendar year. That includes asking about prior employment. In practice:
- At hiring, the person signs a declaration of prior employment (Erklärung über Vorbeschäftigungen) for the current calendar year: employer, period, number of working days.
- The employer adds its own planned days to that. If the total exceeds 70, the employment is subject to social insurance from the start.
- During the engagement, the employer keeps counting. As soon as it becomes foreseeable that the limit will be exceeded, liability for contributions starts from that day, not retroactively.
- If the query is missing or wrong, the employer bears the risk. Deutsche Rentenversicherung specifically checks these declarations during an employer audit (Betriebsprüfung).
For organizers with several events a year, counting their own days is the smaller problem. The bigger one is crew who, in the same summer, also work for the neighboring festival, the municipal hall, and a staffing agency. Only asking reveals those days.
Two short-term jobs at the same time
Two or more short-term engagements are allowed, one after another or at the same time, with no break in between. The working days are added up, and the 70-day limit applies to all of them together. If the person works for two employers on the same calendar day, say catering in the morning and the festival bar in the evening, that day counts as one working day, not two.
Three constellations that come up at festivals:
- Two festivals in the same summer. Allowed, and both employers count the other's days. The declaration of prior employment has to be given again at every hiring, not once a year.
- Short-term job alongside a Minijob with a different employer. Allowed and not added up: the Minijob-Zentrale assesses the two separately.
- Minijob and short-term job with the same employer. Not possible. With the same employer there is one single employment relationship; the person is either a Minijob worker or short-term employed.
Tax: is the 70-day rule tax-free?
No. The 70-day rule exempts from social insurance, not from wage tax. For tax purposes, short-term employment is a normal employment relationship. Two paths:
- Individual wage tax based on the person's electronic wage-tax deduction data. For students with tax bracket I, typical festival earnings usually attract little or no wage tax.
- Flat-rate taxation at 25 percent (Pauschalierung) under § 40a Abs. 1 EStG, if the engagement doesn't exceed 18 consecutive working days, the average wage doesn't exceed €150 per working day, or the engagement becomes necessary at short notice at an unforeseeable time — and the hourly wage is at most €19. The employer bears the flat tax, plus the solidarity surcharge and, where applicable, church tax.
The 18-day threshold for flat-rate taxation is a tax-law limit and has nothing to do with the 70 days of social insurance. Both are checked separately.
What applies in 2027
The time limit stays: 3 months or 70 working days are in § 8 Abs. 1 Nr. 2 SGB IV without an expiry date. What changes on 1 January 2027 are the values around it:
| 2026 | from 1 Jan 2027 | |
|---|---|---|
| Minimum wage | €13.90 | €14.60 |
| Marginal-employment threshold (check of occupational character) | €603 a month | €633 a month |
| Time limit for short-term employment | 3 months or 70 working days | unchanged |
For flat-rate taxation, § 40a EStG (as of October 2026) still names the limits of €19 per hour and €150 per working day. Important for season planning: days are counted per calendar year. The days at the 2026 summer festival don't count toward a new engagement in summer 2027. How to build the next season on that is covered in season planning 2027 for event staff.
Where organizers blow the limit
From practice, in this order:
- No query on prior employment. The form is missing or not evaluated. At audit time, there's no proof, and the organizer pays the contributions retroactively.
- Build and strike not counted. Anyone doing three weeks of build, four festival days, and a week of strike is at 30 days before the season really starts.
- The same person at two entities. An event GmbH and a hospitality GmbH within the same group are two employers, but the days are still added together.
- Overlooking occupational character (Berufsmäßigkeit). A person who moves from festival to festival from May to September, with nothing else going on, is occupationally employed, no matter how many days that adds up to.
- Multi-year framework contracts. A framework contract providing for repeated engagements over more than one year can call the short-term nature into question overall. Better: one fixed-term contract per event.
What that means for planning
The 70 days are a planning figure, not a payroll figure. Anyone who only counts them at month-end close ends up in September with people at 68 days who still have three shifts on the plan. Counting has to happen in shift planning, with the days from the self-declaration as the starting value, tracked time as the actual, and booked shifts as the forecast. Then the decision on whether the person continues as a Minijob or as subject to social insurance from October falls before the shift, together with the person. The same count belongs as a rule in front of every staffing suggestion, as described in AI shift planning for events, and all the way into payroll: how the days reach the payroll office through the 70-day overview and the DATEV interface is covered in automating payroll for event staff. Whether a Sofortmeldung is also needed before the first shift depends on the industry, not on the employment type.
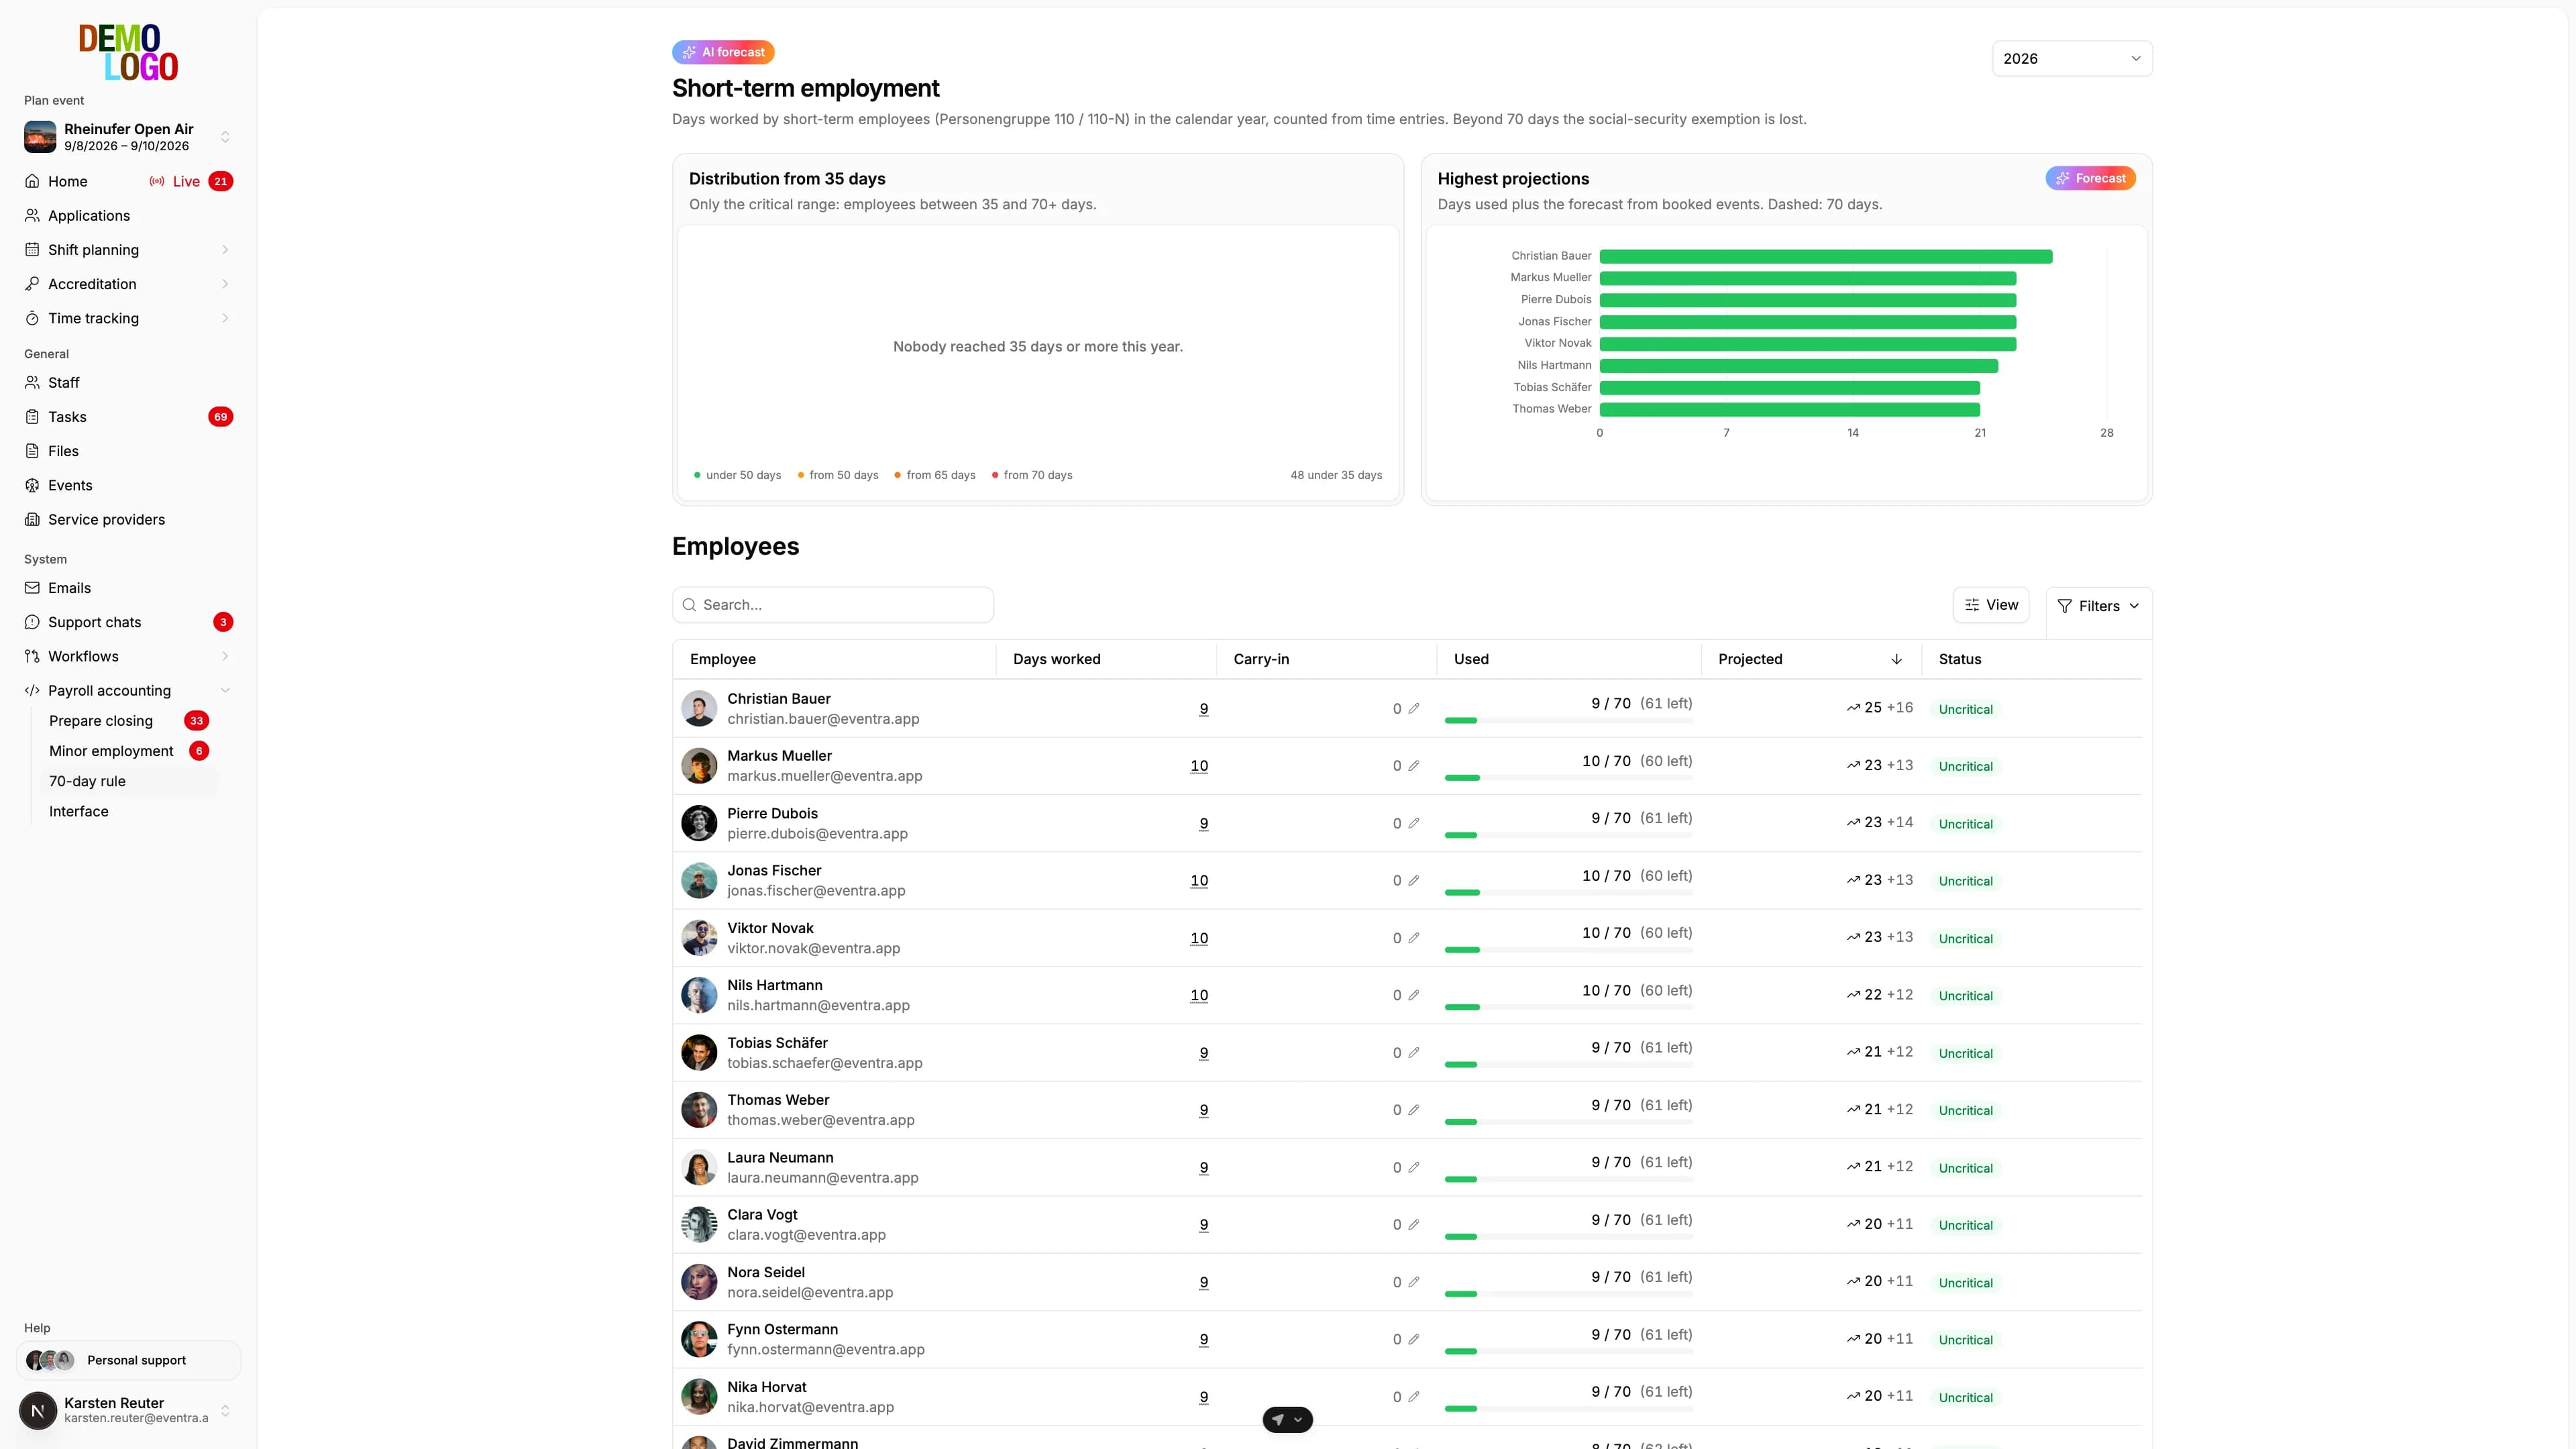
See also: 70-day rule in the documentation glossary and the handbook entry on short-term employment.